Peter Cunningham Has Watched Wall Street for 35 Years — Here's What He Says Actually Builds Wealth
Peter Cunningham has watched investors navigate everything from market crashes and recessions to technology booms and periods of extraordinary growth.
Sept. 16 2026, Published 3:02 p.m. ET

For more than three decades on Wall Street, Peter Cunningham has watched investors navigate everything from market crashes and recessions to technology booms and periods of extraordinary growth.
Through all those cycles, the Siebert Financial wealth manager says one of the most important lessons he has learned has little to do with picking the next hot stock.
It starts with controlling how much you spend.
Cunningham, who began working on Wall Street in 1991 and has more than 35 years of industry experience, works with individuals, families and corporations on investments and broader wealth management strategies. His philosophy is grounded in a straightforward idea: building wealth requires discipline long before it requires sophisticated investing.
The One-Third Rule
Cunningham advocates dividing available income roughly three ways: one-third toward investing, one-third toward savings and one-third toward spending.
In practice, the percentages can vary depending on someone's income and obligations. But Cunningham believes the underlying discipline is critical.
For someone earning $120,000 annually, or approximately $10,000 per month before taxes, allowing housing, insurance, food and lifestyle expenses to consume nearly everything can make long-term wealth creation extraordinarily difficult.
Instead, Cunningham encourages clients to build their lifestyle around consistently setting aside a meaningful portion of their income — potentially $2,500 to $3,000 per month — for saving and investing.
The reason is compounding.
Even returns in the 7% to 8% range can become powerful when money remains invested for decades. That is why Cunningham argues that one of the biggest advantages younger investors possess isn't necessarily greater financial knowledge. It's time.
Time in the Market Beats Timing the Market
That philosophy also shapes Cunningham's approach to volatility.
After working through multiple market cycles, he remains a believer in the old Wall Street principle that "time in the market" generally matters more than attempting to perfectly "time the market."
Market crashes can make selling feel rational in the moment. Booming markets can make investors feel invincible. Cunningham's experience has taught him to be cautious about both impulses.
Instead, investment risk should evolve with someone's life.
Younger investors with decades ahead of them may have greater capacity for equities, ETFs and individual stocks. As investors approach retirement, Cunningham says portfolios typically shift toward a more balanced combination of equities and fixed income.
For clients in their 70s and 80s, the equation can change dramatically, with fixed income potentially representing the majority of a portfolio when preservation and income become the priorities.
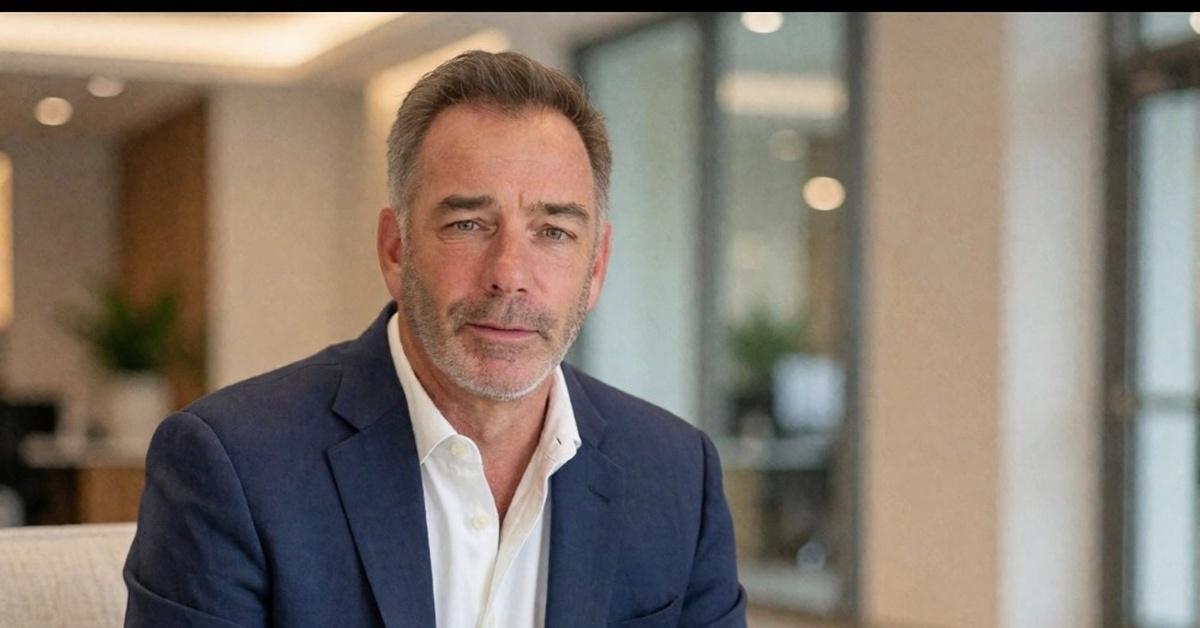
AI Is Making Investors Smarter — But Advice Still Matters
Cunningham is also seeing another major change in wealth management: clients are arriving better informed.
Artificial intelligence platforms such as ChatGPT and Claude, along with increasingly sophisticated investing apps, have given everyday investors access to financial information that once required considerably more research.
Cunningham doesn't view that as a threat to wealth managers.
Instead, he believes it changes their job.
Clients can arrive with an AI-generated analysis, investment idea or portfolio question. The advisor's role is increasingly to provide context, test assumptions and determine how that information applies to the client's actual financial situation.
After 35 years on Wall Street, Cunningham has seen the tools change dramatically. The fundamentals, he believes, haven't.
Spend deliberately. Invest consistently. Adjust risk as your life changes.
And give your money time to work.